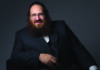

Michael (Dovi) Weiser is the only person I’ve ever interviewed who, in the same conversation, delivered stone-cold business advice and teared up when speaking about his married children. But that combination of vision and heart are exactly what have made him a success in business.
On the stage of real estate, Michael Weiser has played virtually every role in his almost 30-year career. He began as a commercial mortgage banker for GFI Capital before stepping in to manage the company’s national acquisitions and dispositions–handling the purchase and disposition of over 35,000 multi-family units across the country. In the years since then, he has managed billions of dollars in real estate transactions, and now acts as President of GFI Realty Services, a standalone Commercial Real Estate firm based in Manhattan which focuses on investment sales, debt and equity. Over the years the firm has been honored with numerous CoStar Power Broker awards. Basically–if you want to invest or sell in the five boroughs and in real estate hotspots across the country, Weiser is the man to ask about it.
Dovi took some time out of his jam-packed schedule to tell me about his full-bodied career trajectory and give over some plum business—and life–lessons. Enjoy!
I was born and raised in Flatbush and still live two blocks from where I grew up. My mother was an early childhood teacher turned residential real estate broker, and my father is in Chinuch and Kiruv. I’ve always had a natural business streak in me, I went to Brooklyn College and got my degree in accounting. At the time, accounting seemed like the right foundation for understanding business. Economics is to macro; accounting is more micro.
“I got my degree in accounting and got married around the same time in 1996. I interviewed at banks and a few other companies, but everything felt like I’d be put in a box. My father-in-law, Isaac Gross (known in the industry as Allen Gross), was an attorney who founded GFI in the early ‘80s (though back then, it was called Gelt Funding). At the time, he was starting a new venture and he offered me to get involved. That’s how I ended up working in equipment financing, making loans to limited-service hotels. These were small, older hotels, like a Holiday Inn or a Best Western, that stood for reliability. To keep their “flag” , owners had to update their properties to meet brand standards. Many of these owners were doing well, but when they were required to make big upgrades, like changing to electronic card locks, they didn’t have the cash to do it in one shot. We provided financing for these property improvement plans (PIPs), and that’s how I got involved in the business.
“As I spoke with these property owners across the country, I realized that they were getting their mortgages from local banks at high rates, with full personal guarantees. At the same time, the CMBS (Commercial Mortgage-Backed Securities) world was really starting to take off, and GFI had relationships with a few investment banks. We would originate and underwrite the loans, but the investment banks would fund the loans under our name, although they owned them. I’d be talking to these property owners in the Midwest and secondary markets and say, ‘Look, I can do better for you. You don’t have to sign a personal guarantee, and we can give you more money.’ And they would be interested. So, I started doing that, and eventually, I was working with GFI’s Commercial Real Estate team, full time. I left the equipment financing behind because this was a bigger opportunity.
“In 2001, GFI owned a lot of real estate in New York, New Jersey, and Pennsylvania, but my father-in-law wanted to expand further. I was brought into that process, along with a few others, and we started working on these deals. We bought about 2,500 units in Houston, Texas, in one transaction, and after that, I was sort of running acquisitions for GFI on the multifamily side. Between 2001 and 2008, we purchased about 30,000 apartments across seven or eight states. Along the way, we assembled a full team of people.
“I visited most of the properties before we bought them. I arranged the loans on practically all of them, handled capitalization with private equity firms for a good portion of the portfolio, and dealt with some of the private investors. I also worked with the banks and lawyers, negotiating the joint venture agreements, loan docs and overseeing various aspects of the deals. It was all interconnected—I wore multiple hats.
“Then, in 2008, the world changed. Like everyone else, we had to deal with the financial crisis. You put out fires, kick cans down the road, and do whatever you can to survive and fight another day. The key in this business is to do more good deals than bad ones. When people tell me they’ve never done a bad deal, they’re either new to the business or they’re lying. Nobody’s that lucky. You can do all the due diligence in the world, but you can’t control the market.
Up until 2008/2009, the 30,000 units, we owned were all Class B and C. After the financial crisis, we started dipping our toes back into the market by buying non-performing loans and unfinished condo projects in New York. We foreclosed on those properties, finished the construction, and then sold them. Our experience during the downturn showed that with B and C properties, if rents are around $500-$800 and tenants lose their jobs, they’re gone. If you drop rents from $800 to $600 to try and retain tenants, that’s a 25% decrease. You can’t make the numbers work. In these kinds of properties, your profit is in the last few percentage points of occupancy.
“So, we made a decision: we didn’t want to buy B and C properties anymore. We wanted to buy better-quality, Class A or newer properties. The thinking was that these properties wouldn’t have the same functional or architectural obsolescence, and the tenant profile would be more stable. If things went bad again, we could drop rents and stay full, even if we were just breaking even. We wouldn’t make money, but we’d hold onto the property and ride it out. So, we started buying again—thousands of units in Atlanta and Kansas City. Over the next few years, we did quite a few deals in Kansas City, even developing a few properties from the ground up.
“Throughout this time, I was still working as a commissioned salesperson at GFI, doing deals for my own clients while also handling in-house deals and wearing multiple hats. Around that time, the person running the commercial real estate group left. As I had been working with and a part of the team for over 15 years and knew most of the people—I stepped in to run the group.
“As the company grew, it expanded into development, and the hospitality business. Although there were dedicated individuals running those deals, I learned a tremendous amount about those businesses by being part of the financing and capitalization side of things. Hotels offered much higher returns than multifamily properties, although they came with higher risk. As a result, the company was allocateing more capital towards hotels then to multifamily. In an effort to source cheaper capital, in 2014, I spearheaded GFI ‘s first bond offering on the Israeli stock exchange. We weren’t the first to do this, but we were one of the early ones, and though I’m no longer involved, the subsequent offerings continue to fuel GFI Capital’s growth.
“Eventually, the company fully shifted away from multifamily property due to the high prices and moved toward other asset classes. There was less for me to do on the principal side of things, so I focused more on running the brokerage. Around 2018, there were internal restructurings, and my business, the commercial real estate sales brokerage, was spun off into its own company. That’s the long story of how I got to where I am today.”
What are some of the lessons you learned from the crash of 2008?
It’s hard to be objective when the fires are raging and you’re trying to put them out. But looking back, I learned a lot of valuable lessons. We had properties in Houston, Atlanta, Michigan, and South Florida—places where, at the time, most people from our community weren’t doing business. I remember the first time I saw a Class-C apartment complex in Texas. It had nice grass, full landscaping, numerous amenities, a swimming pool, and a playground. Then, you’d go see an apartment building in the South Bronx with basically the same tenant profile, but it looked nothing like that. You might be fooled into thinking the Texas property was better, but the quality of the physical property isn’t what makes it a good investment. It’s about your ability to manage it, buy it at the right price, and collect rent. You can control expenses all you want and try to do things on the cheap, but if you can’t collect rent, it’s worthless. So, while the Texas property may have looked better, the tenants were the same, with the same income levels and challenges—it’s just a different neighborhood.
As the market turned, properties that were 95-98% occupied dropped to 50-60% occupancy overnight, and people just left, often abandoning their belongings. In those states, within two weeks, the marshals are at your door, and tenants are gone. When people lost their jobs, they didn’t stick around—they just left. It wasn’t like New York, where tenants could remain in the apartment for 18 months while the courts and the sheriff sorted things out. These are things you don’t fully understand until you experience them. Suddenly, you can’t pay your bills cover your expenses, let alone your mortgage. And once that happens, it snowballs.
The lesson I took from that time, which became clear later, is that the grass isn’t always greener on the other side—pun intended. The nice appearance of a property doesn’t mean it’s a better investment. What matters is the price you pay and the ability to manage and collect rent. If you buy something at the right price, you can weather the storm. If you overpay, there’s no fixing that. One thing I’ve seen recently is people paying more than a property’s worth because it comes with seller financing or a good assumable loan. Sure, that adds some value, but all you’re doing is giving the seller a premium today and hoping that things catch up by the time you have to deal with it. If not, you’ve got a problem, and there’s no magic formula to bail you out.
The second big lesson I’ve learned is that without local knowledge, you won’t succeed. You need to understand the neighborhoods, and there’s a reason for the old saying “the other side of the tracks.” It’s based on real differences between areas. You can’t just walk into a new market and think you’ll instantly know the good side from the bad side. In New York, for example, frum people don’t think about public schools because we look at shuls, yeshivas, and maybe a pizza shop or a steakhouse. But in other markets, public schools matter. Is it a good school district? How’s the school rated? These are things you have to consider. I remember we were buying a deal in Kansas City. On paper, it seemed great—it was in a good public school district. But what we didn’t realize at first was that the way the school district lines were drawn, the right side of the block belonged to one district and the left side belonged to another. Our property was on the wrong side of the block. That’s the kind of local knowledge you need. Sure, you can get some of that information online today, but you still need to know what you’re looking for.
One of the things I also learned through experience, and you really do have to learn from experience, is something that only crystallized for me later on. Many people think they’re smarter than the ones who came before them, that they could do better. But I don’t buy that. Sure, some people are smarter than others, but there are also people who are just luckier. It reminds me of a story I once heard about one of the Reichmann brothers, who was asked what he attributed his success to. He said it was 95% mazel and 5% skills. When asked what he would change if he started over, he said he’d trade 5% of his skills for more mazel. At the end of the day, you have to recognize that timing and luck plays a role, too.
What are some of the most important assets to have in business?
I always say that the only thing you have is time. Whether you’re a lawyer billing by the hour, learning in kollel, or a stay-at-home mom, you’re selling your time and skills, so you have to make sure you’re putting that time toward maximum output.
It’s true that I’m more interested in big ideas, but I also know that to execute, you have to be able to focus on the details. Even if you’re managing people, you need to understand what they’re doing so you can execute properly. If you don’t understand what someone who’s working for you is doing, it’s a recipe for disaster. It all comes down to this: you don’t get ahead by cutting corners. Sure, you might get by for a while, but if you leave a brick out, the building will eventually fall. It might stand for a couple of years, but it’s going to fall down.
Some people think that in real estate brokerage the most important thing is to be a good talker. But I think it’s the opposite: you have to be a good listener. You learn more by listening. One of the best pieces of advice I ever got, and something I am constantly working on, is when you’re in a meeting and you feel the urge to jump in and say something, count to five. Practice some personal discipline and think, “Should I actually say this?” And most of the time, you’ll find that people aren’t done talking. Especially in real estate—it’s a game of personalities. People want to be heard. Everyone has something to say, and you build relationships by listening.
You never learn by talking—never. The only way to develop trust with clients is by building a relationship, and the only way they’ll trust that you understand their needs is if you’ve actually taken the time to listen to them. That’s the reality. The harder part is applying it but it’s something we all have to try to do.
Is there a special sauce for closing deals?
Every deal is different, i think the key is understanding that everyone has their own objective. Some people, as crazy as it sounds, don’t even care about the facts—they just need to feel like they’ve won. You have clients who are tough negotiators, and they’ll put their foot down because it’s in their nature. Sometimes they do it too soon and have to walk it back. What you need to do is set things up in a way that makes them think it was their idea, that they won.
Sometimes you need to talk to each side separately. It reminds me of the story of the boy who writes a letter home from yeshivah. The father reads it and says to his wife, all disgusted, “Look at this! He’s asking for money and pants!” The mother grabs the letter and says, “No, it says, “Tatty, please send me money and pants.” It’s all about how you read it, and everyone will hear things differently. That’s what sales is—understanding that everyone has a different objective and saying what you need to say in a way that it will be heard.
If you take the time to really understand someone’s objectives, most of the time, barring an impossibility, you can work it out. It might not be easy—you might need to involve other people and share the credit—but that’s part of the process. In this business, so many people want to take all the credit. Yes, it’s important for growth and future deals, but it’s not the only thing. If you’re a team player, the recognition may take longer to come, but when it does, the calls will come to you, not the person who tried to take all the credit.
For example, one of my brokers had a client who got angry and cut off their working relationship. Another opportunity came up where the broker could do a deal and make money from that same client—who wouldn’t even know it was him. He told me, “I’ll do the deal and then I’ll show him.” I said, “No, the best revenge is that you got the check, it cleared, and you made money. You don’t need to tell him.” It’s all about how you define your wins. For me, a win is closing the deal and everyone being happy.
Did your experience working for a larger team, and now running a company, make you a better boss?
You’d have to ask the people who work for me, but there are a few things I’ve made a priority. First, I knew what had bothered people in the past, so I dealt with that right away. Sometimes you have to be the tough guy. It’s not fun, but it’s necessary. At the same time, you have to understand that when people choose to work on commission, it’s a lifestyle choice. Brokers are foregoing a regular paycheck every Friday for the chance to make significant money. So, when someone comes to me and says they want to make $75,000 to 100,000 in this business, I tell them not to take the job. You can find a salary job, work 9 to 5, and in three years, you might be making $90,000 or $100,000, with health insurance, and you won’t have to worry about commissions. You can sleep well at night, knowing that check will always come in.
If you’re coming to work on commission, it’s because you want to make $500,000, $600,000, a million-plus a year, and you’re willing to put the time in. But that also means accepting the trade-off that, to some degree, you’re your own boss. It’s not like Yeshiva, where someone is checking your attendance from 9 to 5. Of course, you need to show up for meetings, and there has to be discipline, but part of the reason people choose to be real estate brokers is because of the lifestyle it offers. For example, Fridays in the summer—whether they’re part of the frum community and heading to the country, or they’re heading to the Jersey Shore or the Hamptons—people want that flexibility. And if they wanted to be in the office every Friday, they’d take a job with a regular paycheck.
I’ve worked on finding the balance. It’s not about letting people get away with whatever they want, but understanding their choices and embracing the fact that this job comes with its pros and cons. If you give people respect and the flexibility they need at times, then not only can you ask for their time and commitment when you need it, but they’ll also give it. I’m a big believer in teamwork. In many firms, the environment is dog-eat-dog, and nobody trusts each other. But I’ve tried hard to foster a different environment where people trust and work together. It wasn’t easy, but I’m proud to say we’ve achieved that. If you ask anyone on my team, they’d all agree.
Like any brokerage, we’ve had people come and go over the years. Some left on their own, and in other cases, we helped them move on. But when you remove the bad apple, the rest of the team thrives. That’s been an important part of creating the culture we have today.
Another key element is that I work with my team, not against them. I don’t compete with my brokers for deals. If I have clients I don’t take someone else’s deal and try to pitch it to them. On the contrary, I introduce my relationships to my brokers and let them run with it. I assist them, stay in the loop, and offer guidance as needed. My role is to run the business and make sure they have everything they need to succeed—whether it’s office support, infrastructure, marketing, or any other resource. Ultimately, it comes down to trust and respect. You can’t buy that, and it’s the foundation of everything we do.
What’s behind your staying power in a business that can be high-stakes and high-stress?
Due to my time at GFI and the Familial relationship, I was given the opportunity to see and touch more types of deals, every part of a transaction, in so many different markets in ways that some of the most accomplished brokers never get to do.Some guys have done more deals, sure, but maybe only as a mortgage broker or only as a sales broker. I had the privilege of being involved on every side of the table, and that lets you see things from a completely different perspective. That collective experience and opportunity is priceless and something for which I am eternally grateful. Coupled with tremendous Seeyata Dishmaya it is the reason for my success.
Because of those experiences, I understand nuances and take care of things before they’re potentially stressful. For example, when we have a buyer and seller agree to a price, Most people would say, “Let’s send out an email, introduce everyone to the lawyers, let them handle the contract, and we’ll sit back and wait for our check.” But I say no. Don’t rely on the lawyer or anyone else to get the deal done for you. It’s your money on the line. If the negotiations hit a snag and you don’t step in, nothing’s going to happen. Sure, the lawyers are going to try on behalf of their clients, but you have the greatest incentive because you only get paid if the deal closes and as you were the matchmaker, you are best positioned to sort out the issue. If you don’t understand the process and stay involved, when there is a problem you will have a hard time fixing it.
That’s what I try to teach my team and the value we bring to our clients: an understanding of the nuances, the details and the process. You only get that understanding with time and experience.
What’s your experience with maintaining your Jewish identity in the secular world of real estate?
I think it comes down to consistency. When you stay true to who you are, over time, people respect it. I started going to places like Kansas City almost 20 years ago (well before many frum people were doing business there). Locals rarely interacted with frum Jews. I never tried to blend in and I don’t hide who I am. I wear my yarmulke everywhere, except maybe in windy places where I’ll use a baseball cap because, well, I don’t have much hair to hold a yarmulke with bobby pins anymore.
One of my first deals was actually a mortgage for a Holiday Inn in Hazard, Kentucky. This was real “Dukes of Hazzard” territory—the boondocks. I was working with a senior GFI broker named Jerry. It was Erev Shabbos, and we had a conference call with the client to go over the loan application. It was winter, so Shabbos was early, and I’m looking at my watch, getting anxious. Jerry wasn’t Jewish, but he knew I had to go. He mouths to me, “How much time do you have?” I said, “About 10 more minutes.” Jerry, being a great mentor, wasn’t going to continue the call without me. So, he apologizes to the client, saying, “Michael needs to go—it’s Friday afternoon…” Before he could finish, the client, a guy named Ben, asks, “Michael, are you Jewish?”
I said, “Yes, sir.”
Then he goes, “How Jewish are you?”
And Jerry responds, “He’s very Jewish.”
There was a pause, and then Ben says, “My best friend Yossi is Jewish—from Tel Aviv.”
Turns out, Ben had met this guy Yossi on a pilgrimage to Israel. Yossi owned a jewelry store in Tel Aviv, and they became such good friends that Ben would fly the Israeli flag on his hotel. When some locals in Hazard asked him, “Ben, how can you fly that flag? Don’t you know they killed Christ?” Ben replied, “I met these people—they didn’t kill anybody.” So, there you go—a guy in Hazard, Kentucky, flying the Israeli flag at his hotel.
Sometimes, you experience the opposite. In Kansas City, there was a deal I was working on. This was a brand new property a developer had built. We signed a contract agreeing to buy it 30 days after he got the certificate of occupancy (CO). But the bottom line is, he was delayed and couldn’t get the CO. We couldn’t close because our banks wouldn’t move forward without it. He was getting very frustrated, and we had a conference call with our lawyers, his lawyers, and the developer. The call got pretty heated, and it turned anti-Semitic. The developer selling the property referred to my attorney as my “Shabbos goy” and other things.
At that point, I told my lawyer, “I’m hanging up now. We’re prepared to close as per the provisions of the contract, as soon as the seller meets his obligations.” And that was that. We hung up, and eventually, we closed the deal once everything was sorted. Later on, we bought the phase two site from him and built it ourselves.
A couple of years passed, and I heard that this gentleman had been in some kind of accident. I don’t remember the exact details, but I do remember when it was—after the Pittsburgh synagogue shooting in 2018. That’s when I got an email from him, out of the blue, basically apologizing and saying how hate has no place in the world. It floored me. This was someone who had gone from making anti-Semitic comments to writing a heartfelt apology.
After that, I sent him a holiday card one year, and every now and then he’d send me an email about a deal. Then, on October 9, 2023, I got another message from him. He knew I go to Israel often, and he was aware that I was there. He wrote, “I’m thinking about you and your family. I pray you and everyone else in Israel stays safe. I’ve got your back, whatever you may need. I’m ready.” I responded politely, thanking him for his message. A few days later, on Friday, October 13, he wrote again, saying, “Do you want me to come fight with you? My hand will be on your shoulder the entire time.”
This is just one of those strange stories I’ve accumulated over the years. We had met many times. He saw me as a frum Jew, not hiding anything. He said what he said back then, and I believe he meant it at the time. But after the Tree of Life synagogue shooting, he had a kind of religious awakening. It’s one of those things—you think someone is full of Jew-hatred, but deep down if you act as a Frum Jew is supposed to act, you may lead them to change their tune and you will fund they aren’t necessarily morally corrupt or bankrupt.
How do you balance work with the rest of your life?
The hardest part is balancing everything—what I call all the extracurriculars. Someone once said to me, “The busy man always has time.” I don’t know who said it, but there’s some truth to it. I mean, I’m not Superman. There are so many people out there doing incredible things, and I’ve been inspired by many of them to do more. It’s not just one specific person, but overall, when you see what people can achieve if they set their minds to it, it’s motivating. I’m a big believer in just doing. I rarely say no, though sometimes I look back and think maybe I should’ve said no to this or that.
I took over a girls’ high school in Flatbush two years ago because it was about to close. I started my shul with The Rav, 25 years ago and I’m still the gabbai and managing the finances. There are many other causes and organizations I’m involved with such as Co- Founding The MFO Summit an annual real estate networking conference to benefit the Shalom Torah Academy scholarship fund. Occasionally, I think about letting go of something because you have to let others take over as well. You can’t be a control freak. But at the same time, I think a lot of the imbalance and juggling contributes to who you are. The person who does nothing never gets asked to do anything. People always call the person who’s already doing something. Whether it’s in community life, family life, or work life, if you’re active, you’re going to get the phone calls.
If you want to be in the game, you have to be fully in it. That means being busy and juggling a lot. There were years when I didn’t leave the office before 10 o’clock at night. There were days I stayed until 2 or 3 in the morning, working on something. But those days have changed. A few years ago, I made a conscious decision to stop because I realized my kids were growing up, and there’s no pause button on that.
The thing is, the problems will still be there in the morning, and at home, the kids will go to sleep. Sometimes you just need to come home, take a break, and pick things back up later. But it’s a choice you have to make. You can’t just say, “I’m going to work on three deals – that’s enough money,” because you don’t know that all three deals will close. You have to constantly work on new deals and new opportunities.
In a way, not trying to balance everything, just diving into it all, has led to so many opportunities. A lot of the people I work with now are people I got to know through extracurricular situations, not business-related ones. When you build a connection with someone through working on a project or being part of an organization together, you form a bond that transcends work. Sometimes you don’t even have to ask for business—it just comes naturally. It’s like if you’re a plumber and someone you know needs plumbing work, they’ll just call you. Why wouldn’t they?
To read more, subscribe to Ami